Late payment rarely becomes a crisis in one move. It appears in a growing overdue balance, another promised date that slips, and more finance time spent pursuing cash the business has already earned.
For many U.S. finance teams, the immediate constraint is capacity. Consistent follow-up, dispute resolution, and clean account records require daily attention, but adding permanent headcount is not always the quickest or most flexible answer.
That has changed how CFOs view credit control. The function is no longer judged by collection activity alone; it is judged by whether cash becomes more predictable without weakening customer relationships.
This article explains what outsourced credit control covers, how credit control, credit management, and debt collection differ, and what senior finance leaders should test before appointing a provider.
Outsourced credit control services place defined parts of the collections cycle with an external specialist. The provider works within agreed policies for customer contact, overdue-account management, disputes, escalation, cash allocation, and reporting, while the business retains sensitive credit and commercial decisions.
The outsourced credit control process should address the points where cash is actually being delayed. Typical responsibilities include:
Customer credit checks: Assessing creditworthiness and applying the business’s approved policy before terms are extended.
Invoice follow-up and collections: Managing reminders and customer contact through an agreed cadence, with each promise and next action recorded.
Payment plans and dispute resolution: Coordinating billing issues, documenting agreed plans, and escalating decisions that require commercial approval.
Cash allocation: Matching receipts promptly so the ledger, aging report, and collection priorities remain reliable.
Bad-debt prevention: Monitoring risk indicators and escalating accounts before balances become materially harder to recover.
The strongest credit control outsourcing solutions create a disciplined flow from account review to follow-up, dispute resolution, and escalation. The objective is not simply more contact; it is better prioritization and clearer ownership of the reasons invoices remain unpaid.
Where Credit Management Outsourcing Extends the Scope?
Credit management outsourcing goes further than overdue-account follow-up. It can include customer risk assessment, credit-limit administration, account monitoring, collections strategy, and portfolio-level reporting. Because these activities can influence who receives credit and on what terms, decision rights matter as much as scope.
A provider can apply policy, prepare risk analysis, and maintain the process, but management should retain approval thresholds, exceptions, and commercial risk appetite. Credit outsourcing works best when those boundaries are explicit and visible in governance reviews.
Why CFOs Outsource Credit Control: The Value Beyond Collections?
For U.S. finance leaders, the case for credit control outsourcing is less about moving work and more about making cash conversion more dependable. Three outcomes matter most:
Cash-flow visibility: Regular account review, follow-up, and escalation give finance leaders a clearer view of expected receipts and the issues delaying them.
Earlier risk escalation: Defined triggers bring deteriorating accounts to management attention before balances become significantly harder to recover.
Consistent customer handling: Agreed contact standards and escalation paths reduce ad hoc chasing while protecting important commercial relationships.
The value therefore sits beyond collections volume. A well-run service makes exceptions visible, clarifies who owns them, and gives the CFO a more reliable basis for working-capital decisions.
Read this case study to see how we transformed F&A operations for a leading global real estate company.
What Sets the Best Credit Control Services Companies in the USA Apart?
The best credit control outsourcing companies are not defined by how many reminders they send. They stand out in the way they prioritize accounts, manage exceptions, protect customer relationships, and make performance visible to finance leaders.
End-to-End Credit Management Capability
The strongest providers don’t just chase overdue invoices. They manage the full credit cycle from credit vetting to collections, dispute resolution, and cash allocation.
They also integrate cleanly with the wider order to cash cycle, which gives CFOs better visibility into every stage of the process. This end-to-end view helps reduce blind spots, keeps ledgers accurate, and ensures customers don’t fall through the cracks.
Automation-Driven Credit Control Processes
Technology should support the work rather than become the proposition. Useful tools prioritize accounts, automate routine reminders, flag exceptions, and give teams a consistent record of customer activity.
The test is whether technology shortens the route from an overdue balance to the right action, while keeping human judgment where a dispute or customer relationship requires it.
Proven Results in Reducing Bad Debt
Track record matters when comparing top credit control outsourcing companies. Evidence should show how account prioritization, dispute resolution, and escalation improved outcomes in a comparable customer portfolio.
Their structured approach to follow-ups, escalations, and risk identification plays a big role in reducing bad debt with outsourced credit control. This is often one of the clearest benchmarks CFOs use to evaluate performance.
Custom Solutions for CFOs Across Industries
Every industry has its own credit pressures. High-volume invoicing in staffing and manufacturing looks nothing like long-cycle receivables in healthcare, real estate, or SaaS.
The best credit control partners tailor workflows, cadence, escalation paths, and reporting formats to match how each sector operates. This flexibility is what makes them valuable to CFOs looking for scalable outsourced credit management models.
Strong Reporting and Compliance Framework
Top-tier providers don’t leave CFOs guessing. They offer real-time dashboards, risk scoring, account-level visibility, and audit-ready documentation.
This level of reporting gives finance leaders confidence that every action taken by their outsourced team is traceable, compliant, and aligned with internal credit policies. It also allows CFOs to stay in control without getting buried in operational detail.
Why U.S. Businesses Choose QX Global Group for Credit Control
QX Global Groupoperates as an outsourced credit control service provider in the USA, supporting customer follow-up, disputes, cash allocation, account reporting, and scalable delivery under agreed client policies.
End-to-End Outsourced Credit Control Services Powered by Automation
QX manages the full credit cycle — from credit checks and collections to dispute handling and cash allocation. Automation keeps reminders consistent, reduces delays, and removes manual gaps that often slow down internal teams.
Skilled Credit Controllers Working to Client Policies
Accounts are handled by specialists working to approved customer-communication standards, escalation rules, and applicable compliance requirements.
Structured Delivery for Mid-Market and Enterprise Clients
QX uses defined contact schedules, escalation routes, and reporting to make overdue balances and collection activity easier to manage.
Strong Expertise Across Multi-Location and High-Volume AR Environments
From staffing and manufacturing to healthcare, real estate, and SaaS, QX supports companies that manage thousands of invoices and operate across multiple locations. Workflows are tailored to fit complex, high-volume credit cycles.
Analytics-Driven Dashboards for CFO Visibility
CFOs get real-time dashboards, cleaner aging insights, risk indicators, and audit-ready documentation. Everything is built to give finance leaders the visibility they need without pulling them into daily collections work.
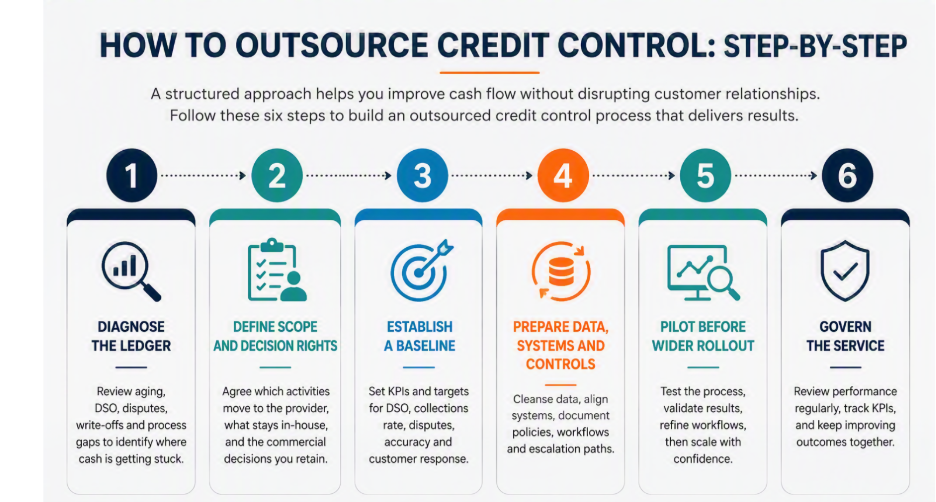
A controlled transition starts with the reason cash is being delayed, not with a provider’s standard service list. The following sequence keeps ownership and customer risk visible:
image
Credit Control vs. Credit Management vs. Debt Collection
These services are related, but they do not solve the same problem. Credit control manages routine payment follow-up and overdue accounts. Credit management is broader, covering credit policy, risk assessment, limits, monitoring, and collections. Debt collection generally begins when normal credit-control activity has failed and a balance requires specialist recovery or legal escalation.
A business looking to outsource credit should therefore start with the stage at which the process is breaking down. Using debt collection for routine follow-up can damage customer relationships; using ordinary credit control for seriously delinquent accounts can delay recovery. Credit services outsourcing is useful only when the chosen service matches the problem.
How to Choose the Right Credit Control Outsourcing Partner in 2026?
When comparing providers, senior finance leaders should look beyond capacity and price. The question is whether the partner can improve the outsourced credit control process while fitting the business’s customer strategy, systems, controls, and escalation model.
Industry Experience and Domain Expertise
A strong partner understands your sector’s billing cycles, customer behaviours, dispute trends, and credit pressures. Industry familiarity often leads directly to faster resolutions and fewer aged receivables.
Technology and Automation Capability
Automation is now central to modern credit control. Look for providers using workflow tools, AI-driven reminders, and risk insights to speed up collections and eliminate manual gaps.
SLA-Backed Performance Guarantees
Clear commitments around follow-up cadence, dispute management timelines, and collection outcomes give CFOs the confidence that the partner is accountable and performance-driven.
Integration with ERP and CRM Systems
Seamless integration with platforms like NetSuite, Sage Intacct, QuickBooks, SAP, Oracle, or Salesforce helps avoid duplication, improves accuracy, and creates a unified view of the order-to-cash cycle.
Reporting Transparency
Real-time dashboards, clean aging reports, escalation logs, and customer-level insights ensure finance leaders retain full visibility even when operations are outsourced.
Compliance and Data Security
Credit control touches sensitive financial and customer information. Strong controls, documentation discipline, and adherence to U.S. regulatory standards are non-negotiable.
Ability to Scale with Invoice Volumes
A good partner grows with you. As your customer base expands or seasonal volumes fluctuate, the outsourced team should maintain speed and consistency without stretching internal resources.
What’s the Bottom Line?
Credit control is most valuable when it makes cash more predictable without turning every overdue account into a customer confrontation. That requires consistent execution, clear escalation, and reliable data.
Q1. What does a credit control outsourcing company do?
A credit control outsourcing company manages the full credit cycle on behalf of a business, including credit checks, invoice follow-ups, dispute handling, collections, and cash allocation. These providers help improve consistency, reduce overdue balances, and strengthen overall credit risk management.
Q2. Is outsourcing credit control cost-effective for U.S. businesses?
Yes, outsourcing is often more cost-effective than maintaining an in-house credit team. It reduces hiring and training expenses while giving companies access to skilled credit controllers, automation tools, and structured processes that improve recovery rates.
Q3. How do U.S. outsourced credit control services ensure compliance with industry regulations?
Top providers follow federal and state collection laws, maintain audit-ready documentation, and use secure data-handling practices. Their teams are trained in U.S. accounting and compliance requirements, ensuring that every interaction stays within regulatory standards.
Q4. Can outsourced credit control companies handle high-volume or multi-location operations?
Yes, leading providers specialise in high-invoice-volume environments and multi-location businesses. They use scalable teams, automation workflows, and centralised reporting to manage complex credit cycles without losing consistency.
Q5. How do the best outsourced credit control providers improve cash flow and reduce bad debt?
They improve cash flow through consistent follow-ups, automated reminders, and accurate aging insights. Their structured workflows and early-risk identification help in reducing bad debt with outsourced credit control while delivering more predictable inflows.
Q6. How Much Do Outsourced Credit Control Services Cost in the USA?
Outsourced credit control cost depends on account volume, aging, dispute levels, systems, contact requirements, service levels, and delivery approach. Compare the fee with internal staffing, management time, technology, and inconsistent follow-up.
Q7. What does credit management outsourcing include?
It can include credit checks, policy administration, risk monitoring, collections, disputes, cash allocation, and reporting. The client should retain approval thresholds and sensitive commercial decisions.
Q8. How do credit control, credit management, and debt collection differ?
Credit control manages routine follow-up. Credit management also covers policy, risk, and limits. Debt collection addresses seriously delinquent balances after normal collection activity has failed.
Q9. How quickly can a business outsource its credit control function?
Timing depends on ledger quality, systems, customer complexity, and scope. A controlled transition maps the process, confirms access and policies, and tests a defined portfolio before wider rollout.
Q10. Which outsourcing firms are known for reducing DSO and improving cash collection performance?
Strong providers combine consistent follow-up, early dispute resolution, accurate account data, and clear escalation. Finance leaders should ask for evidence from comparable portfolios and measure results against a baseline.
Nishant Timbadia is a seasoned finance professional with over 12 years of experience in the outsourcing industry, specialising in end-to-end F&A operations. At QX, he leads delivery across Credit Control, Order to Cash, R2R, P2P, and intercompany processes. With a strong background in payroll, billings, and management accounts, Nishant is known for driving process optimisation, managing high-performing teams, and ensuring seamless transitions from setup to go-live.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept”, you consent to the use of ALL the cookies.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.