Topics: Build to Rent, Finance & Accounting
Posted on August 13, 2026
Written By Nishant Kumar
When John Lewis walks away from something, the rest of the sector tends to sit up and take notice.
In early 2026, the retailer did just that. It shelved its plans for 1,000 rental homes across three sites, in West Ealing, Bromley and Reading. Each one already had planning behind it. And yet all three were quietly parked. The reason was refreshingly honest. The scheme had been dreamed up in a world of cheap borrowing and steady returns. That world had moved on. In plain terms, the numbers no longer worked.
Now, you would expect a story like that to be about money running dry. It isn’t. If anything, the opposite is true. A record £2.2 billion poured into build to rent in the second quarter of 2026 alone.
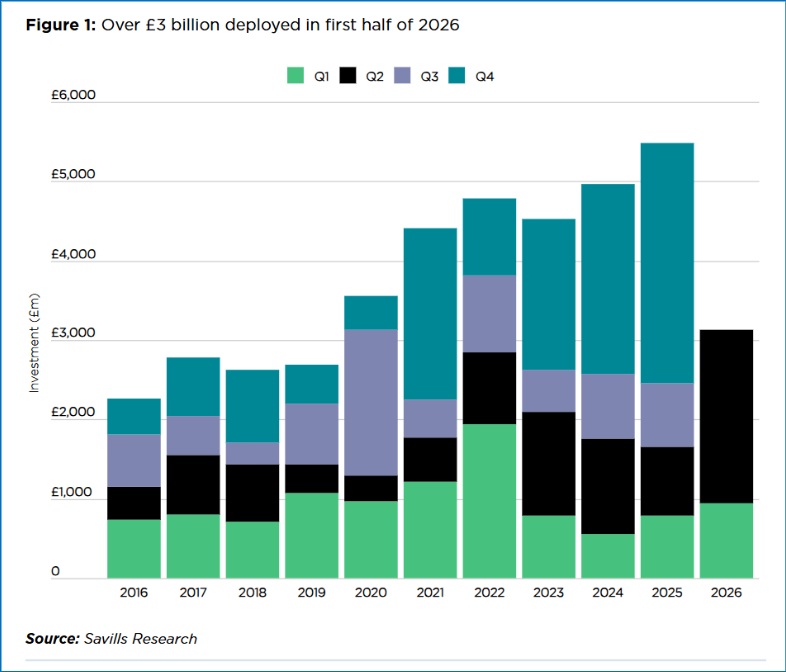
The appetite is clearly there. Planning is not really the villain either. Consents have actually been ticking up. So here is the odd part. Despite all that cash, and all those permissions, starts on site fell by a huge 79% in the year to June.
The cash is there. The consents are there. The homes, somehow, are not. That is the strange knot at the heart of the build to rent (BtR) sector UK today.
This blog pulls that knot apart. It looks at why so many approved schemes never leave the ground. And it shows where the smart money is quietly finding its edge.
So if the money is flowing, why does the sector feel so stuck? The honest answer is that the headline number tells you only half the story.
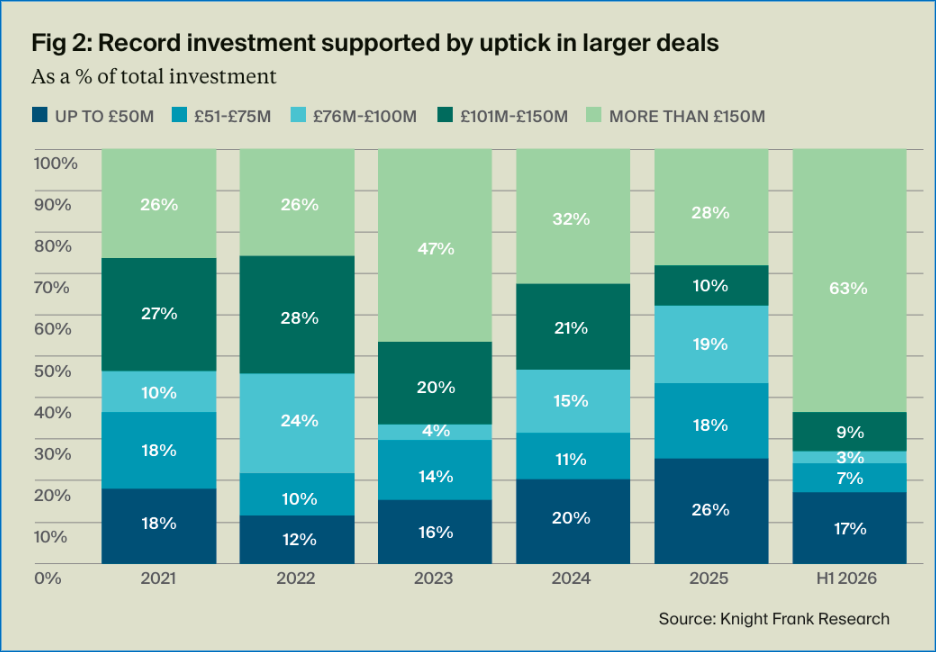
Yes, a record sum went into build to rent this year. But look at where it landed. Most of it went on buying finished, tenanted buildings. Very little went on funding new ones. The big cheques were written for just a handful of deals. In the second quarter, two deals alone made up £1.5 billion of the spend. As Knight Frank put it, record volumes should not be mistaken for a broad-based recovery.
There is a pattern in who is spending, too. North American money funded 60% of investment in the first half of the year. And that money is chasing safety. It wants assets that already work, with rent coming in and tenants in place. The risk and wait of new multifamily housing development holds far less appeal.
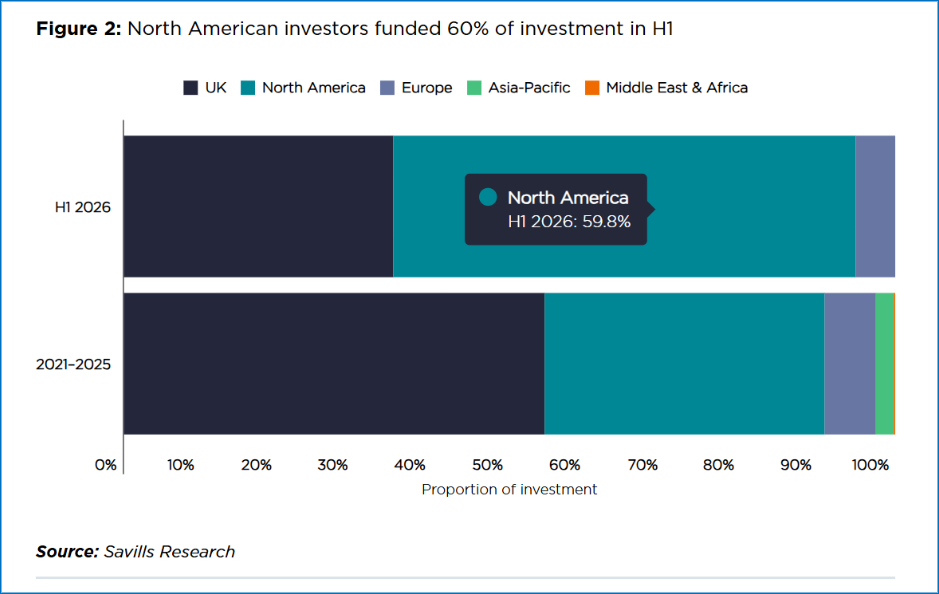
That tells you plenty about wider build to rent investment trends. Institutional real estate investment has not lost its nerve. It has simply changed its target. The appetite is real. It is just pointed at the finished article, not the building site.
Which brings us back to the awkward question. If the cash is there, and the will is there, why aren’t the cranes?
Here is where most people point the finger at planning. It is the easy villain. But the data does not back it up. Approvals are actually going up, not down. In the year to June 2026, the number of homes in planning rose by 4%. So the permissions are being handed out. The problem is what happens next.
Look a little closer and a quieter warning sign shows up. The number of schemes at the detailed application stage, the ones closest to breaking ground, fell by 3% in a single quarter. In other words, the near-term layer of the UK build to rent pipeline is thinning, even as the headline planning figure grows. That is the gap that matters.
The truth is that a consent on paper is not the same as a scheme you can actually build. And the distance between the two has never felt wider. This is the real test of consented scheme viability, and it is where most of the current BtR development challenges live. Three things tend to sit in the way:
Clear each of those and you have startable housing supply. Fail on any one, and a perfectly good consent just sits there, doing nothing.
Boards love a headline number. The trouble is, the headline here flatters the truth. The whole UK residential development pipeline now sits at over 310,000 homes. That sounds healthy. But a pipeline is only as good as the stage that actually turns plans into homes, and that stage is quietly draining.
So here is a simple way to read it. Track the pipeline by stage, the way you would track DSO or occupancy. One glance tells you where the trouble really sits.
| Pipeline stage | Direction (year to Q2 2026) | What it actually tells you |
| Homes in planning | ▲ up 4% | Consent is not the bottleneck |
| Detailed applications | ▼ down 3% (on the quarter) | The startable layer is thinning |
| Under construction | ▼ down 21% | The engine is shrinking |
| Starts on site | ▼ down 79% | Almost nothing new is beginning |
Look at the top two rows against the bottom two. Consent is rising. Building is falling off a cliff. That is the whole story in four lines. A good build to rent accounting services partner would flag that shape long before it ever showed up in a completions report, because the money stops moving at the start, not at the finish.
And the drain is not new. Completions have now outrun starts for ten quarters in a row. Every one of those quarters, the BtR construction pipeline UK gets a little lighter. Slowly at first. Then all at once. That is how startable housing supply disappears, not with a bang, but one unstarted scheme at a time.
When leasing ends and finance begins, revenue can slip through the gap. See where ownership often gets lost.
Here is the part that rarely makes it onto a board slide.
Every home has a lead time. What you start today, you finish years from now. So a collapse in starts is not just a bad quarter. It is a hole in supply for the back half of this decade.
Knight Frank puts it plainly: the drop in new starts means delivery is expected to fall further to the end of the decade.
Read that slowly. The shortage everyone is bracing for has, in effect, already been booked.
And it is not only about cost. Policy is adding its own weight. Asked about rent controls, investors did not mince words:
That is not caution. That is a warning shot. The build to rent delivery pressure building today owes as much to uncertainty as to concrete and steel.
Here is the quiet twist, though.
Scarcity is not only a risk. For the operator who can still get homes out of the ground, it is a moat. As new supply dries up, the near-term UK residential development pipeline keeps thinning. Institutional real estate investment keeps drifting toward whatever is already finished and safe.
Which leaves a real opening for anyone brave enough to build.
So where does the edge actually sit now? For years, the answer was simple. Win the demand. Secure the capital. The rest would follow.
But look around today. Both are everywhere. Neither is the thing holding anyone back.
The new edge is quieter. It is the ability to turn a consent into operationally ready rental assets. To move a scheme through viability, gateway and funding, and out of the ground.
Think of it as two eras:
A real example: Manchester and Salford
Together they have delivered more BtR homes than any market outside London. Not by luck, but by maths. Lower land values, tax relief on multiple dwellings, and the ability to grow rents during the build all kept the sums working. When the numbers hold, homes get built.
That is the real lesson. Most BtR development challenges are not about bricks. They are about numbers. Build costs. Working capital. The margin that keeps a scheme alive at the very point where others give up.
Protect that margin, and consented scheme viability holds. Lose it, and the whole thing stalls. This is the unglamorous part that decides who builds and who waits. It is finance discipline, not a hard hat.
It is also where QX quietly fits. We already sit inside the sector’s finance and back-office operations, helping real estate and BtR operators keep schemes moving when the maths gets tight.
So back to where we began. John Lewis did not walk away because the money dried up. It walked away because the scheme, on paper, no longer stacked up.
That, in a sentence, is the whole story.
The build to rent supply gap is not really about capital. It is not quite about planning either. It is a startability problem. The homes are consented. They just are not getting built.
And that changes what winning looks like. The operators who treat build to rent delivery pressure as a core skill, not a site problem, are the ones who will hold more operationally ready rental assets when the next cycle turns.
The rest will still be holding permissions.
If your own schemes are stuck somewhere between consent and start, it is worth understanding why. Book a consultation call with us, and we will talk it through.
The gap has flipped the old logic. Money is not scarce, with a record £2.2 billion invested in Q2 2026, yet starts on site fell 79% in the year to June. Consents exist, but homes are not getting built. That mismatch now shapes competitive advantage across the build to rent (BtR) sector UK.
Today’s starts are tomorrow’s completions, so falling starts create a supply hole years ahead. Knight Frank expects delivery to drop further to the end of the decade. With completions outrunning starts for ten straight quarters, the UK build to rent pipeline keeps thinning, tightening future supply and lifting the value of homes that do get built.
Because capital is now everywhere, and delivery is not. The real skill is turning a consent into operationally ready rental assets, moving a scheme through viability, gateway and funding. When most investors chase finished buildings, the operators who can actually build hold a genuine edge that money alone no longer buys.
A weakening pipeline squeezes future income. Fewer starts today mean fewer completions later, so investors risk shrinking supply, rising competition for finished stock, and softer returns. Policy adds to it: 100% of surveyed investors said they would cut BtR investment if rent controls arrived, deepening the build to rent supply gap further still.
By focusing on deliverability, not just deals. The strongest operators protect scheme viability where others stall, controlling build costs, working capital and margins. Manchester and Salford show it working, delivering more BtR homes than any market outside London because the maths held. Handling build to rent delivery pressure is now a core skill, not a site issue.
Because consents are rising while starts collapse, so permission is no longer the constraint. Startable housing supply, schemes that can actually break ground, is what is genuinely scarce. Whoever can convert consented schemes into homes controls what everyone else will be short of, making startability the sector’s real competitive advantage.
By treating viability as a live, ongoing discipline. Tight control of build costs, working capital and cash flow keeps a scheme bankable at the exact margin where others give up. Strong build to rent accounting services and back-office operations protect consented scheme viability long before problems surface in a completions report.
QX Global Group sits inside the sector’s finance and back-office operations, supporting real estate and BtR operators at scale. From accounting to portfolio-wide reporting, we help teams keep schemes moving when the maths gets tight, turning operational and financial complexity into steadier, more predictable delivery across growing rental portfolios.

Education:

Nishant Kumar is a senior commercial leader with 20+ years of experience supporting hospitality and accommodation businesses through technology-enabled outsourcing and operational transformation. At QX Global Group, he works with property owners, asset managers, and hospitality leaders across the UK and Europe to improve profitability, modernise back-office operations, and build scalable operating models. His expertise spans finance and accounting, payroll, and digital enablement for multi-property and franchise-led hospitality organisations, with a strong focus on cost optimisation, standardisation, and automation-led efficiencies.
Expertise: Hospitality and accommodation outsourcing, Multi-entity finance transformation, Shared services and global delivery models, Automation-led cost optimisation, Strategic commercial advisory
Originally published Aug 13, 2026 02:08:03, updated Aug 18 2026
Topics: Build to Rent, Finance & Accounting
02 Sep 2026
Hospitality has become one of the most data-rich industries in the world. Every reservation, room sa...
Read More27 Aug 2026
In June 2026, Morgan Stanley and Ridgeback paid £1.045 billion for Metra Living, L&Q’s re...
Read More20 Aug 2026
On a June morning this year, retirement housing found itself in the one room operators would rather ...
Read More06 Aug 2026
You never applied for a banking licence. Yet if your customers routinely pay you late, that’s ...
Read More